Suzanne Dyer
Phone
(310) 528-7480
Email
[email protected]
If you bought or refinanced your home when mortgage rates were exceptionally low, you may be sitting on something more valuable than you realize.
Your mortgage itself may be a selling feature.
Certain government-backed mortgages, including many VA, FHA and USDA loans, may be assumable. That means a qualified buyer may be able to purchase the property and take over the seller's existing mortgage balance, interest rate and remaining loan term, subject to the loan program, servicer approval and buyer qualification.
For a homeowner with a mortgage in the 2%, 3% or low-4% range, that could create a meaningful advantage when competing for buyers in a higher-rate environment.
For Palos Verdes homeowners, however, there is another important part of the calculation: equity.
A low-rate assumable mortgage can be extremely attractive, but the buyer still has to cover the difference between the remaining mortgage balance and the purchase price.
That is why I think assumable financing should be analyzed as part of a home's overall selling strategy rather than treated as a one-size-fits-all solution.
An assumable mortgage allows an approved buyer to take over an existing home loan rather than obtaining an entirely new mortgage for that portion of the purchase.
The buyer generally assumes the existing:
The buyer must still satisfy the requirements of the particular loan program and servicer.
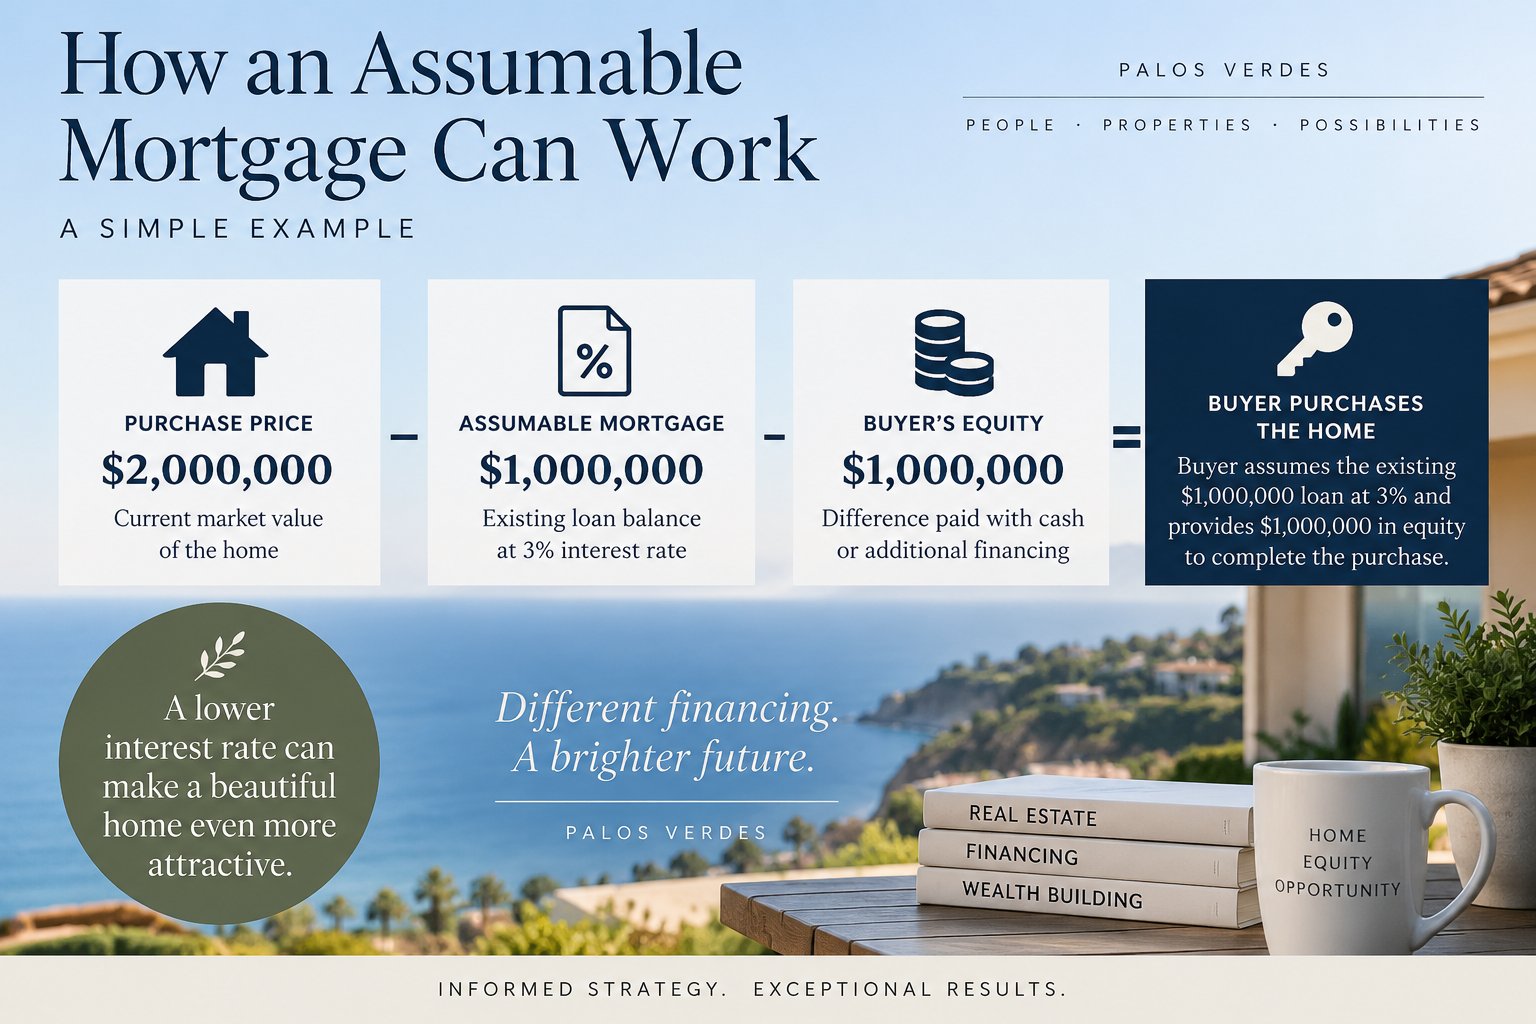
Imagine a Palos Verdes homeowner has:
If the loan qualifies for assumption and the buyer is approved, that buyer could potentially retain the 3% rate on the existing $1 million mortgage balance.
The buyer would still need to cover approximately $1 million of equity between the assumed mortgage and the purchase price.
But the ability to finance a significant portion of the purchase at a substantially below-market rate could make that particular home more attractive than another property at a similar price.
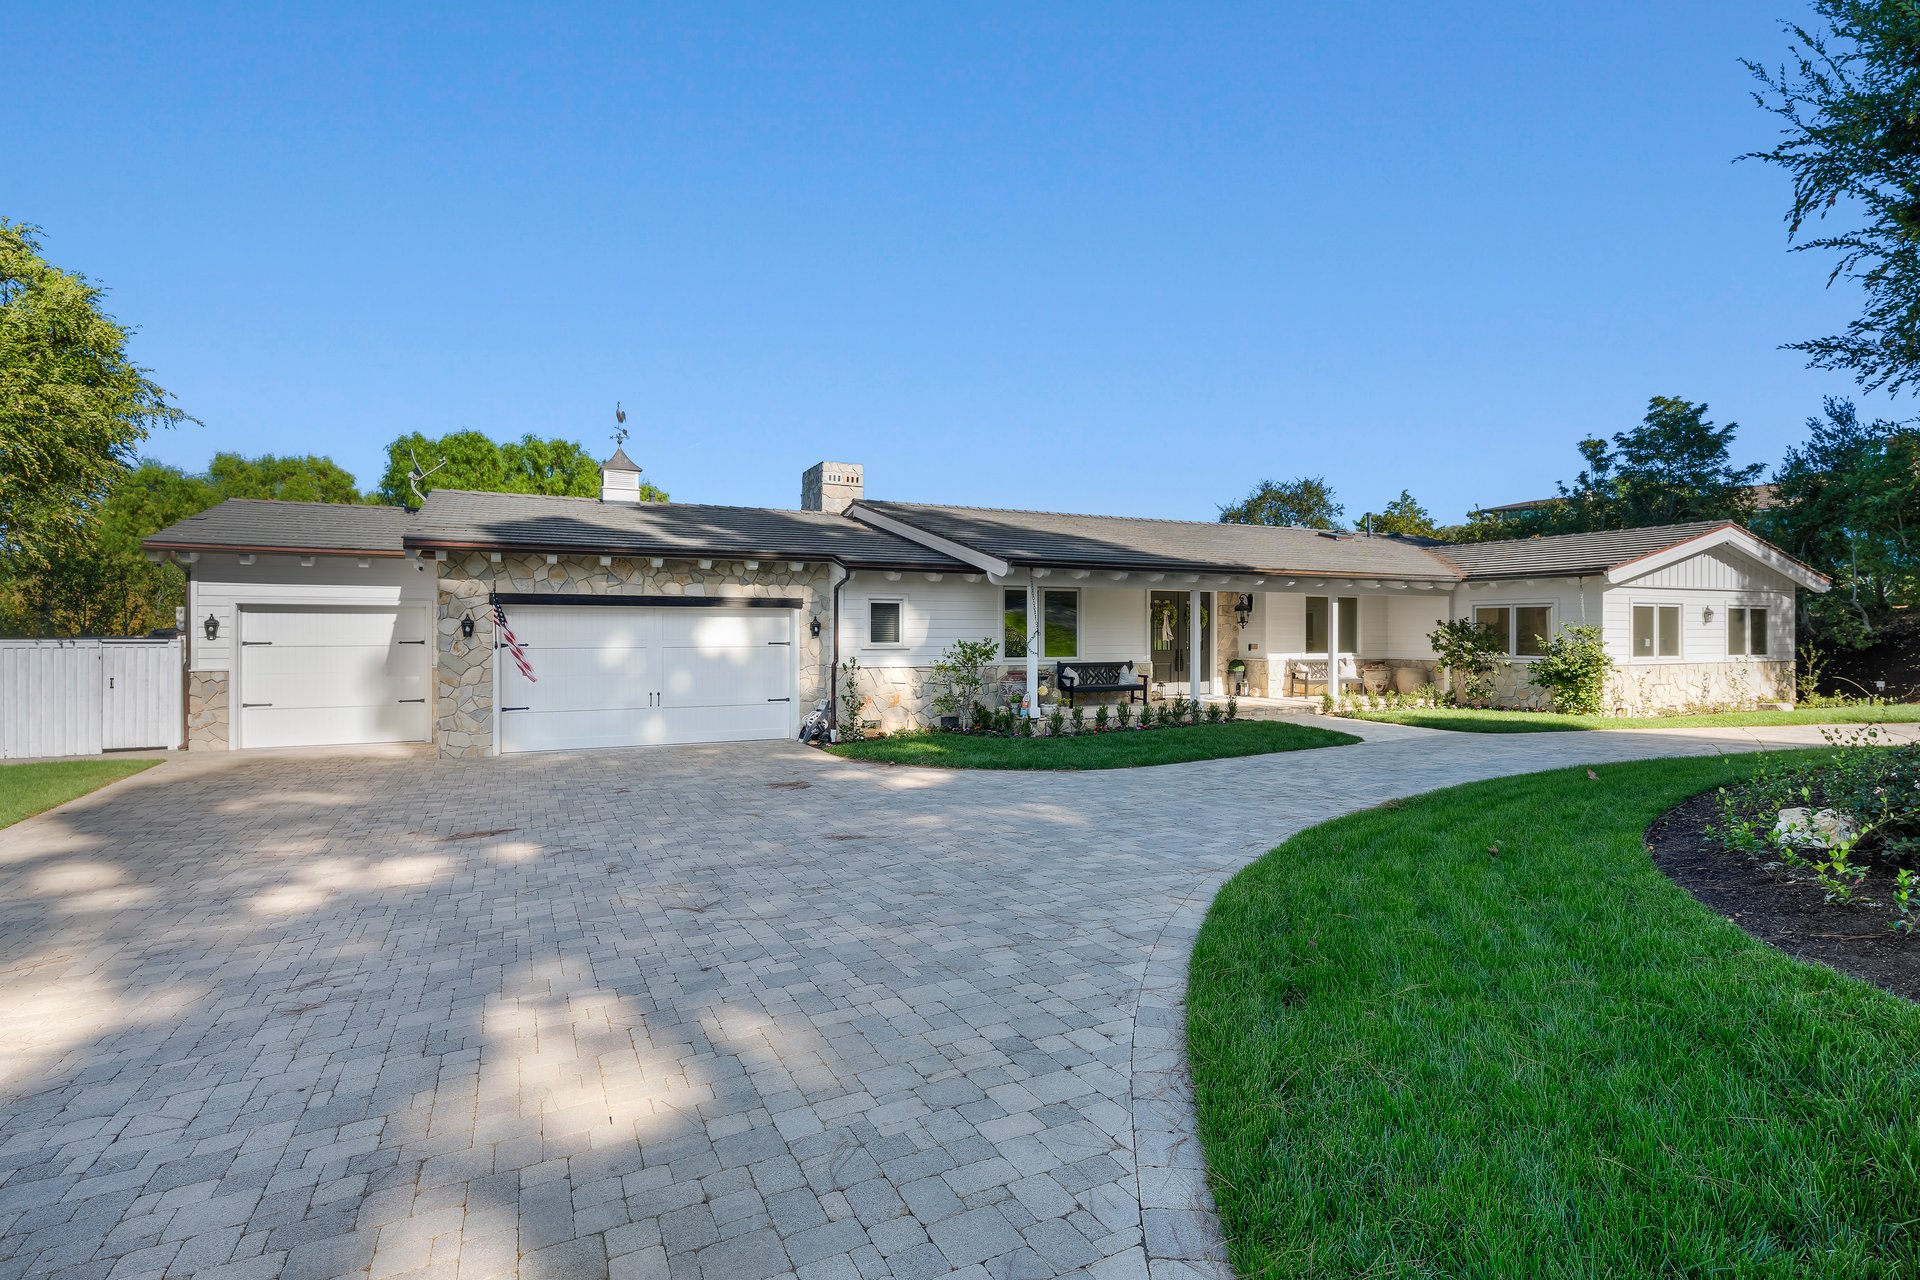
When preparing a home for sale, we naturally think about features such as:
But in the right situation, the seller's financing may also be worth investigating.
A favorable assumable loan could potentially:
It does not automatically make the property worth more.
It does mean that the financing may be another asset to consider when developing the selling strategy.
VA-guaranteed mortgages are assumable subject to VA requirements and approval.
The person assuming the loan must generally be creditworthy and take responsibility for the mortgage.
Importantly, the buyer assuming a VA loan does not necessarily have to be a veteran.
But veteran sellers need to understand the difference between:
Assumption of the loan
and
Substitution of VA entitlement.
If an eligible veteran assumes the mortgage and has sufficient VA entitlement to substitute for the seller's entitlement, the original veteran seller may be able to have that entitlement restored.
If there is no substitution of entitlement, the seller's VA entitlement can remain tied to the existing loan until that loan is paid off.
That can affect the seller's ability to use the full amount of VA entitlement for another purchase.
For that reason, a VA homeowner should speak directly with the loan servicer and an experienced VA lender before marketing the assumption.
FHA-insured mortgages are generally assumable, although the requirements depend partly on when the loan originated.
For most modern FHA mortgages, the buyer will need to meet applicable credit and qualification requirements.
If you have an FHA mortgage with a particularly low interest rate, it is worth asking the loan servicer about the exact assumption requirements before putting the home on the market.
Certain USDA Rural Development loans can also be transferred with an assumption, subject to USDA and lender requirements.
The buyer may be able to assume the existing guaranteed loan under the rate and terms contained in the existing promissory note if the transfer is approved.
Again, the specific loan and borrower must qualify.
Usually not in the same way.
Many conventional fixed-rate mortgages contain a due-on-sale clause, which generally allows the lender to require the mortgage to be paid off when ownership of the property transfers.
There are exceptions and certain loan structures that may permit assumptions, but a homeowner should never assume that a conventional low-rate mortgage can simply be transferred to a new buyer.
Check with the loan servicer first.
This is where assumable mortgages get particularly interesting in Palos Verdes.
Suppose a homeowner owes only $700,000 on a property that is now worth $2.5 million.
The seller may have a wonderful 2.75% mortgage.
But the buyer would still need to account for approximately $1.8 million between the existing loan and the purchase price.
Depending on the buyer, that difference might be covered through:
For some buyers, that may be entirely manageable.
For others, the size of the equity gap may reduce the practical benefit of the assumable mortgage.
That is why I would analyze the numbers before deciding how prominently to advertise the financing.
Possibly.
If I were preparing a Palos Verdes home for sale today and the owner told me there was a low-rate VA, FHA or USDA mortgage on the property, I would want to investigate that loan before finalizing the marketing plan.
I would look at:
If the numbers showed a meaningful advantage, we could then determine whether and how to incorporate the assumable financing into the property's marketing.
If you are thinking about selling a home in Palos Verdes Estates, Rolling Hills, Rolling Hills Estates or Rancho Palos Verdes, pull out your current mortgage statement before assuming that your loan is simply something that will be paid off at closing.
Look at the:
Then contact the loan servicer and ask whether the mortgage is assumable and what the qualification and approval process would be.
Your low mortgage rate may not change the strategy for selling your home.
But in the right situation, it could become another valuable tool for attracting the right buyer.
An assumable mortgage is a home loan that may allow a qualified buyer to take over the seller's existing mortgage rather than obtaining a completely new loan for that portion of the purchase.
The buyer generally assumes the remaining balance, interest rate and loan term, subject to lender or agency approval.
Yes. VA-guaranteed loans can be assumed if the applicable VA requirements are satisfied and the assumption is approved.
The person assuming the mortgage must generally meet VA credit and underwriting requirements.
Not necessarily.
A non-veteran may be able to assume a VA loan if the buyer qualifies.
However, this can have important consequences for the veteran seller's VA entitlement.
If an eligible veteran buyer substitutes his or her VA entitlement for the seller's entitlement, the seller may be able to have the entitlement restored.
If there is no substitution, the original veteran's entitlement may remain tied to the loan until it is paid off.
Generally, yes.
FHA-insured mortgages are assumable, although qualification requirements and restrictions can depend on when the loan originated.
Most buyers assuming modern FHA loans must satisfy applicable credit requirements.
Certain USDA Rural Development mortgages may be assumed subject to USDA approval and borrower qualification.
The terms depend on the particular loan and transfer.
Most conventional fixed-rate mortgages are not freely assumable because they contain due-on-sale provisions requiring the loan to be paid when the property changes ownership.
There are exceptions, so homeowners should verify the terms of their individual mortgage with the loan servicer.
Usually not.
The buyer assumes only the remaining balance of the seller's existing mortgage.
If a home is worth $2 million and the remaining assumable mortgage is $800,000, the buyer still needs to cover the remaining $1.2 million through cash or another permitted financing source.
The larger the seller's equity, the larger the amount the buyer must fund outside the assumable mortgage.
That does not necessarily make the assumption unattractive, particularly for buyers with substantial cash, but the equity gap needs to be analyzed carefully.
Not automatically.
The property's market value is still primarily determined by factors such as location, condition, size, lot, views and comparable sales.
However, favorable assumable financing can potentially make a property more attractive to certain buyers and help differentiate it from competing homes.
Only after verifying the loan's assumability and understanding the requirements.
Before advertising a specific interest rate or assumption opportunity, the seller should confirm the loan type, balance, rate and assumption process directly with the servicer.
If the financing creates a meaningful advantage, it can then become part of the marketing strategy.
Start by checking your mortgage statement and loan documents to determine whether you have a VA, FHA, USDA or conventional loan.
Then contact your mortgage servicer and ask:
“Is my current mortgage assumable by a purchaser of the property, and what are the requirements for an approved assumption?”
Ask for the answer and the assumption instructions in writing whenever possible.
It can in the right situation.
Palos Verdes homes often have substantial equity, so the most important question is not simply whether the mortgage is assumable.
The better question is:
How much of the purchase price can a buyer finance at the seller's existing low rate, and how will the buyer fund the remaining equity?
That calculation determines whether the existing mortgage is likely to be a meaningful selling advantage.
Suzanne Dyer
Strand Hill | Forbes Global Properties
Serving Palos Verdes and the South Bay since 1990
CA DRE #01054310
If you´re listing or selling real estate in the Palos Verdes Peninsula and surrounding areas, put a winning real estate professional to work for you.
Let's Connect